

Blogs
The global crane rental market is projected to climb steadily, advancing from 11,700 Million USD in 2020 to 17,200 Million USD in 2025 and anticipated to reach 29,400 Million USD by 2035. This evolution is fueled by major infrastructure projects, rapid urbanization, and the adoption of advanced crane technologies. The upward trend reflects operators’ shift to asset-light models and increasing fleet modernization across regions.
Read More - https://bussinessinsights.com/research-report/global-crane-rental
Construction leads the application segments in the global crane rental market for 2025, driven by robust growth in infrastructure, commercial buildings, and housing. Oil & gas and shipping/marine follow, supported by expansion in offshore projects and global trade. The mining, utilities, and transportation sectors continue to contribute, enabled by project complexity and equipment requirements.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-crane-rental
Frequently Asked Questions
Who are the key players in Global Crane Rental industry?
The top five players in the global crane rental industry include Sarens NV, Mammoet, Lampson International LLC, Bigge Crane and Rigging Co., and Maxim Crane Works. These companies are known for their extensive fleets, advanced lifting solutions, worldwide operations, and expertise in handling large-scale projects across construction, energy, and industrial sectors.
What is the Global Crane Rental growth?
The global crane rental market has witnessed steady growth, with a CAGR of over 4% from 2021 to 2024. Recent drivers include Maxim Crane Works expanding its fleet to meet rising demand in North America, particularly from infrastructure and renewable energy projects, boosting overall industry momentum.
Which segment accounted for the largest Global Crane Rental share?
The construction segment accounted for the largest share in the global crane rental market. Driven by rapid urbanization and large infrastructure developments, especially in Asia Pacific and North America, construction projects continue to demand high-capacity cranes for bridges, buildings, and complex engineering works.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Solid-State Battery Market Hits $160M in 2025, Projected 36.78% CAGR to $1.43B by 2032
By PW Consulting, 2026-09-16
Navigating the Solid-State Revolution: Strategic Imperatives for 2026 and Beyond
The global energy storage landscape is undergoing a paradigm shift. As lithium-ion technology approaches its theoretical limits, solid-state batteries (SSBs) have emerged as the definitive next-generation solution, promising unprecedented energy density, enhanced safety, and faster charging capabilities. However, the transition from laboratory breakthrough to commercial scale is fraught with complex supply chain dynamics, regulatory hurdles, and intense competitive maneuvering. For industry leaders navigating the 2026 fiscal year, understanding the nuances of this market is not merely an option—it is a strategic necessity.
Solid State Chip Battery Market
Our latest comprehensive market research, Solid State Batteries Market: Global Industry Outlook 2026-2032 , provides a granular dissection of this rapidly evolving sector. This article serves as a strategic preview, highlighting the critical macro-trends and competitive forces that will define investment decisions and R&D roadmaps in the immediate future.
The Trajectory of Growth: A Macro Perspective
The momentum behind solid-state technology is no longer theoretical; it is reflected in hard financial data. The market has demonstrated explosive growth over the past half-decade, signaling a tipping point in commercial viability. Based on our analysis of historical performance and projected trajectories, the sector has moved from nascent experimentation to tangible revenue generation.
In 2020, the global market valuation stood at approximately 39.45 million USD. By 2025, this figure has surged to 160.0 million USD, reflecting a compound annual growth rate that underscores the accelerating adoption rates across key verticals. Looking ahead, the forecast period from 2026 to 2032 indicates continued aggressive expansion. We project the market size to reach 222.25 million USD in 2026, climbing steadily to exceed 1.4 billion USD by 2032. This growth trajectory is underpinned by a CAGR of 36.78 percent, highlighting the robust demand drivers emanating from both the automotive and consumer electronics sectors.
For stakeholders, these numbers represent more than just market size; they indicate the velocity at which capital is flowing into the ecosystem. The jump from 2025 to 2026 alone suggests that initial commercialization phases are successfully translating into scalable revenue streams. However, volume alone does not guarantee success. The distribution of this value across technologies, applications, and geographies reveals a fragmented landscape where strategic positioning is critical.
Competitive Landscape: The Race for Commercialization
The SSB market is characterized by a diverse array of players, ranging from established automotive giants to specialized technology startups. Our report profiles key companies that are actively shaping the industry standard. The competitive dynamics are not just about who has the best chemistry, but who can secure supply chains, meet regulatory certifications, and achieve mass-production timelines.
Automotive Leaders and Battery Specialists
Traditional automotive powerhouses are leveraging their vertical integration to accelerate SSB deployment. Toyota Motor Corporation, based in Tokyo, remains a leading developer of sulfide-based all-solid-state batteries. Their recent achievement of Japan METI certification for automotive-grade solid-state battery cells from Prime Planet Energy & Solutions in February 2026 validates thermal runaway resistance, a critical milestone for mass production targeting EVs by 2027-2028. Similarly, Panasonic Holdings Corporation in Osaka is collaborating with Toyota to enhance safety and energy density in EVs, reinforcing the Japan-centric push toward sulfide electrolytes.
In China, CATL Co., Ltd. continues to assert its position as a global leader in battery technology, advancing solid-state and semi-solid solutions for higher energy density and safety. Meanwhile, ProLogium Technology Co., Ltd. in Hsinchu, Taiwan, is targeting GWh-scale production capacity for automotive and industrial applications.
South Korea remains a critical hub for battery innovation. Samsung SDI Co., Ltd., headquartered in Suwon, is developing pouch-type all-solid-state batteries for physical AI and automotive applications, targeting mass production in 2027 with advanced safety and power output. LG Energy Solution, based in Seoul, is concurrently developing solid-state battery technologies for automotive and energy storage applications.
North American innovators are also making significant strides. QuantumScape Corporation in San Jose is developing ceramic-separator lithium-metal solid-state batteries, with QSE-5 cells validated for Volkswagen BEV platforms and 1,000-cycle testing. Solid Power, Inc., based in Louisville, is partnering with BMW, Ford, and Samsung SDI for next-generation EV and other markets.
Niche Innovators and Industrial Applications
Beyond the automotive heavyweights, specialized firms are carving out niches. Blue Solutions SAS in Clermont-Ferrand, France, produces solid-state batteries for industrial and transport applications, holding IATF 16949 certification and delivering joint development agreements and A-samples. Donut Lab in Finland has announced the world's first all-solid-state battery ready for commercial OEM production, with initial deployment slated for Verge Motorcycles in Q1 2026.
Solid State Batteries Market
These developments illustrate a market that is branching out. While EVs remain the primary volume driver, industrial transport and specialized AI hardware are becoming viable early-adopter segments.
Recent Developments and Strategic Timelines
The pace of recent announcements underscores the urgency for market participants. In March 2026, Samsung SDI unveiled its first public pouch-type all-solid-state battery sample at InterBattery 2026 for physical AI applications, targeting mass production in the second half of 2027. This follows Donut Lab's February 2026 announcement regarding commercial OEM readiness.
These timelines are critical for procurement and partnership strategies. Companies aiming to integrate SSB technology into product lines for the 2027-2028 model years must engage with suppliers now. The gap between sample validation and mass production is narrowing, but capacity constraints remain a significant risk factor.
Supply Chain Vulnerability and Regulatory Headwinds
While the growth projections are optimistic, the path to 2032 is lined with geopolitical and operational complexities. Our research highlights several structural friction points that could alter cost structures and availability.
Raw Material Constraints
The chemistry of solid-state batteries dictates specific supply chain dependencies. Sulfide solid electrolytes, a leading candidate for high-performance applications, use lithium sulfide as a key component. Prices for these materials remain elevated due to limited global supply and specialty chemical production requirements. Furthermore, manufacturing solid-state batteries often requires inert-atmosphere processing for sulfide electrolytes. Our analysis estimates this increases production costs by 15-20 percent compared to liquid-electrolyte systems, creating a higher barrier to entry for cost-sensitive applications.
Geopolitical and Regulatory Pressures
National security and sustainability concerns are reshaping trade flows. China's export controls on battery materials, including those relevant to solid-state battery electrolytes, took effect in November 2025. This regulation directly impacts the availability of critical inputs for manufacturers outside of China.
In Europe, the Battery Directive and related critical raw materials regulations emphasize sustainability and reduced dependence on concentrated supply chains for solid-state technologies. Compliance with these directives will require transparency and potentially localized sourcing strategies.
In the United States, tariffs on Chinese lithium-ion battery components and imports, including those affecting solid-state supply chains, reached up to 156 percent composite rates as of April 2025. These tariffs fundamentally alter the economics of cross-border supply chains, potentially encouraging near-shoring or friend-shoring of production capabilities.
Market Concentration and Fragmentation
Despite the long list of active participants, the market remains relatively fragmented. Our data indicates a CR3 of 18.7 percent and a CR5 of 23.5 percent. This low concentration suggests that no single entity currently dominates the value chain, offering opportunities for new entrants or specialized partners to capture niche value. However, it also implies that consolidation may be on the horizon as economies of scale become paramount to meet the cost targets required for mass adoption.
The segmentation data reveals where the current value is being generated. In terms of technology, Thin Film Battery technology currently commands a significant share of the revenue mix compared to Portable Battery solutions, reflecting the maturity of certain solid-state applications in niche electronics versus broader power storage. Regarding applications, Consumer & Portable Electronics currently account for a larger portion of market revenue than Electric Vehicles, although the latter is expected to drive the majority of volume growth in the latter half of the forecast period. Geographically, the Asia Pacific region continues to lead in revenue contribution, followed by Europe and North America, aligning with the location of key manufacturing hubs and demand centers.
Why This Report Matters for 2026 Decision-Making
In a market moving at this velocity, general industry knowledge is insufficient. Strategic decisions regarding capital allocation, supplier partnerships, and R&D focus require precise, validated data. The Solid State Batteries Market: Global Industry Outlook 2026-2032 report is designed to provide that clarity.
Our research goes beyond surface-level trends. It offers a deep dive into the operational realities of the supply chain, the specific technical milestones achieved by key players, and the regulatory frameworks that will govern market access. By analyzing the interplay between raw material costs, manufacturing complexities, and geopolitical tariffs, we provide a risk-adjusted view of the market potential.
For automotive OEMs, the report details the readiness levels of various suppliers and the implications of certification timelines. For investors, it maps the competitive landscape to identify consolidation opportunities and technology winners. For policy makers and industry associations, it clarifies the supply chain vulnerabilities exposed by recent export controls and tariff adjustments.
Accessing the Full Intelligence
The solid-state battery market is poised to redefine energy storage over the next decade. The window to establish competitive advantage is open, but it is closing faster than anticipated. Companies that delay their strategic planning risk being locked out of supply chains or forced to adopt inferior technologies due to capacity constraints.
This article has outlined the macro trajectory, the key players, and the external pressures facing the industry. However, the specific segmentation data, detailed regional analysis, and granular forecasts contained in our full study are essential for building a robust business case. The complete report provides the detailed breakdowns of revenue splits, specific growth drivers per segment, and comprehensive company profiles that are necessary for actionable strategy.
To secure your organization's position in this evolving landscape, we invite you to access the full Solid State Batteries Market research publication. Download the complete report to gain the competitive edge required for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Solid State Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DNA Microarray Market Hits $2.2B by 2025, Growing 8.91% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the DNA Microarray Market: A 2026 Decision-Maker's Preview
Introduction
The global DNA microarray market has matured into a critical infrastructure layer for genomic research, clinical diagnostics, and pharmaceutical development. As organizations navigate an increasingly complex landscape defined by technological convergence, evolving regulatory frameworks, and shifting reimbursement paradigms, the ability to translate macro-level market intelligence into actionable corporate strategy has never been more essential. This executive overview serves as a strategic preview to our comprehensive market research publication, outlining the fundamental dynamics that will shape investment, product development, and competitive positioning decisions throughout 2026 and beyond.
Companies operating in the life sciences ecosystem face a pivotal moment. The market has demonstrated consistent expansion over the past five years, transitioning from a research-heavy toolset to a diversified platform supporting clinical applications, companion diagnostics, and precision medicine initiatives. Understanding where value is being created, which segments are accelerating, and how competitive boundaries are being redrawn requires a disciplined analytical approach that goes beyond surface-level observations. The following analysis frames the strategic questions that our full report addresses with granular data, proprietary modeling, and scenario-based forecasting.
Market Trajectory and Structural Growth Dynamics
The historical performance of the DNA microarray market reflects a steady compound annual growth pattern, with the total addressable market expanding from approximately 1.57 billion USD in 2020 to an estimated 2.22 billion USD by 2025. This progression underscores sustained demand across both established research institutions and emerging clinical diagnostic channels. Looking forward, our baseline projections indicate that the market will continue its upward trajectory through the 2026 to 2032 forecast horizon, with an anticipated compound annual growth rate of 8.91 percent. By the end of the forecast period, the market is expected to surpass 4 billion USD, representing a significant expansion in both volume and strategic relevance.
This growth cannot be attributed to a single driver. Instead, it emerges from the interplay of several structural forces: the continued integration of microarray platforms into clinical genomics workflows, expanding applications in pharmacogenomics and targeted therapy selection, and the ongoing modernization of diagnostic laboratory infrastructure. Simultaneously, technological refinement in probe design, hybridization efficiency, and data analysis pipelines has extended the operational lifespan of microarray-based workflows even as next-generation sequencing technologies advance. Rather than competing directly, microarray platforms now occupy a distinct value proposition centered on high-throughput, cost-effective, and standardized screening for defined genomic targets.
Strategic planners must recognize that this trajectory is neither uniform nor automatic. Growth will be unevenly distributed across application verticals, technology types, and regional ecosystems. Our full report provides detailed segmentation analysis that isolates these variability patterns, enabling decision-makers to identify where capital allocation, partnership development, and market entry timing can be optimized. The macro figures provide context; the segment-level intelligence provides direction.
Competitive Landscape and Strategic Positioning
The market structure exhibits moderate concentration, with the top three firms collectively accounting for approximately 41 percent of total revenue and the top five representing roughly 48 percent. This concentration level indicates a market that has moved past the early fragmentation phase but remains open to innovation-driven disruption and regional specialization. Several key enterprises anchor the competitive landscape, each pursuing distinct strategic pathways aligned with their technological portfolios and target end-markets.
- Illumina, Inc. , headquartered in San Diego, California, continues to leverage its established position through the Infinium platform family, which delivers genotyping and methylation arrays tailored for both clinical and research applications. The company's strategy emphasizes integration with broader genomic ecosystems, positioning microarray-based workflows as complementary components within end-to-end laboratory pipelines.
- Agilent Technologies, Inc. , based in Santa Clara, California, maintains a focused presence through the SurePrint G3 and GenetiSure Dx platforms. These custom and comparative genomic hybridization plus SNP microarray solutions are designed for clinical genomics and diagnostic testing environments, reflecting a deliberate emphasis on regulatory-aligned diagnostic workflows and laboratory efficiency.
- Thermo Fisher Scientific, Inc. , operating from Waltham, Massachusetts, sustains its competitive footprint through the Applied Biosystems and Affymetrix microarray platforms alongside the SwiftArrayStudio automated system. These offerings address genotyping, pharmacogenomics, and gene expression profiling, with recent product launches reinforcing the company's commitment to automation, throughput optimization, and streamlined laboratory integration.
Beyond these established players, recent activity in the immunoassay and multiplex microarray space signals ongoing diversification. In early 2025, AliveDx submitted two separate FDA 510(k) premarket notifications: one for the MosaiQ AiPlex Celiac Disease multiplex microarray in February, and another for the MosaiQ AiPlex CTDplus Multiplex Microarray targeting autoimmune connective tissue disease diagnosis in April. A subsequent submission for the MosaiQ AiPlex Vasculitis multiplex microarray followed in September 2025. These filings underscore a broader industry trend in which microarray-based multiplexing is increasingly viewed as a viable pathway for expanding diagnostic panels with standardized, high-throughput processing capabilities. In October 2024, Thermo Fisher Scientific advanced this automation narrative by launching the SwiftArrayStudio next-generation microarray analyzer, paired with Axiom PharmacoPro and PangenomePro arrays designed to accelerate genotyping and pharmacogenomics profiling.
Competitive strategy in this market no longer revolves solely on platform performance metrics. It increasingly depends on the alignment between assay design, regulatory clearance pathways, reimbursement architecture, and laboratory adoption economics. Our full report dissects these competitive vectors, mapping product portfolios against application demand curves and regional regulatory environments, so that stakeholders can assess where incumbents hold durable advantages and where emerging entrants may carve out defensible niches.
Regulatory, Reimbursement, and Quality Infrastructure Dynamics
Policy and reimbursement developments exert a direct influence on market adoption curves, particularly as microarray applications migrate from research settings into regulated clinical workflows. Several recent institutional actions illustrate the shifting landscape that laboratories, manufacturers, and investors must monitor closely.
Effective October 1, 2024, the Centers for Medicare and Medicaid Services implemented new CPT codes that directly affect microarray-associated testing economics. The introduction of code 0020M addresses oncology CNS tumor methylation analysis conducted via microarray, while code 0396U pertains to pre-implantation genetic testing evaluation of 300,000 DNA SNPs by microarray. These coding actions signal formal recognition of specific microarray-driven workflows and create clearer billing pathways that can affect laboratory utilization decisions. At the same time, cytogenomic microarray analysis remains governed under CPT codes 81228 and 81229 when specified criteria for constitutional chromosomal abnormalities are satisfied, with current Carelon Medical Benefits Management guidelines, updated in 2026, explicitly prohibiting additional separate payment for duplicate testing under CMS policy. Such reimbursement boundaries shape utilization patterns, influence test menu design, and affect the financial calculus of clinical laboratories evaluating platform investments.
Parallel to reimbursement evolution, quality control standardization continues to advance. The U.S. Food and Drug Administration's MAQC and SEQC project initiatives remain active in refining quality control standards for microarray data used across drug discovery, clinical practice, and regulatory decision-making. These efforts reinforce data reliability expectations and establish benchmarks that manufacturers and testing laboratories must incorporate into their validation processes. For strategic planners, this means that regulatory quality infrastructure is not merely a compliance concern but a competitive differentiator, particularly in applications where data reproducibility and cross-site comparability influence adoption.
These dynamics illustrate that market success increasingly depends on navigating a multi-dimensional environment where technical capability, coding and reimbursement alignment, and quality standardization converge. Our full report maps these interdependencies in detail, providing scenario analyses that help organizations anticipate how shifts in coding policy, payer coverage, and quality expectations could alter demand trajectories for specific application categories.
Strategic Decision Framework for 2026 and Beyond
Organizations evaluating their positioning in the DNA microarray market should approach 2026 planning with a framework that balances near-term operational realities against longer-term structural shifts. Several strategic dimensions warrant focused attention.
First, product and portfolio strategy must account for the divergence between research-driven volume and clinically oriented value capture. While research applications continue to provide baseline demand and platform visibility, clinical diagnostics, pharmacogenomics, and specialized genotyping workflows increasingly represent higher-margin, higher-growth opportunities. Companies need to determine how their offerings align with these diverging pathways, whether through platform customization, assay menu expansion, or integration with automated laboratory systems.
Second, geographic deployment strategy should be informed by regional variations in regulatory maturity, laboratory infrastructure, and reimbursement accessibility. Markets are not uniform in their adoption trajectories, and a single global plan rarely captures the local nuances that determine implementation success. Strategic players are increasingly tailoring their market entry and expansion approaches to regional diagnostic ecosystems rather than assuming linear global diffusion.
Third, partnership and ecosystem positioning will remain critical. As laboratories consolidate workflows and seek integrated solutions that reduce turnaround time, minimize manual handling, and ensure data consistency, the value of complementary partnerships rises. This includes relationships with automation providers, bioinformatics solution developers, reference laboratory networks, and regulatory consulting entities. Competitive advantage increasingly accrues to organizations that can connect their core microarray capabilities to broader laboratory value chains.
DNA Microarray for Agriculture Market
Fourth, investment and capital allocation decisions should incorporate scenario planning that accounts for the variability inherent in regulatory coding updates, payer coverage adjustments, and technology substitution pressures. Forecasting models that treat the market as a single, predictable growth curve risk obscuring the segment-specific inflection points that actually determine returns. Our full report supplies the segment-level detail and scenario structures needed to stress-test assumptions and align resource deployment with realistic demand pathways.
What Our Full Market Research Report Delivers
The preview above outlines the strategic terrain, but the complete market research publication provides the analytical depth required for concrete decision-making. The report includes detailed revenue and volume projections segmented by technology type and application category, with year-by-year forecasts spanning the full 2026 to 2032 period. It examines regional market structures across all major geographic markets, identifying where concentration, growth acceleration, and competitive intensity diverge. It profiles the leading market participants with operational summaries, recent product and regulatory milestones, and strategic positioning assessments. It also integrates the reimbursement and regulatory developments that affect commercial viability, translating policy actions into market impact narratives rather than isolated factual statements.
Importantly, the report does not simply aggregate data. It contextualizes it. Each section is designed to answer specific strategic questions: which application categories are most likely to sustain durable growth, where automation and workflow integration are reshaping adoption economics, how competitive boundaries are likely to shift as new diagnostic panels advance through regulatory channels, and what factors should inform market-entry timing and resource prioritization. By connecting macro trends to segment-level dynamics and competitive actions, the publication aims to function as an operational intelligence tool rather than a static reference document.
Conclusion
The DNA microarray market in 2026 represents a landscape of disciplined growth, evolving clinical integration, and intensifying strategic competition. Macro indicators confirm sustained expansion, but the real strategic value lies in understanding how that expansion distributes across technology types, applications, regions, and competitive tiers. Organizations that approach the market with granular intelligence, scenario-aware planning, and a clear view of reimbursement and regulatory dynamics will be better positioned to allocate resources effectively, develop resilient product strategies, and capture value as the industry continues its transition toward more standardized, clinically integrated genomic workflows.
DNA Microarray Market
For decision-makers seeking to move beyond high-level trends and ground their strategy in segment-level evidence, competitive benchmarks, and forward-looking scenario analysis, the full market research report offers the comprehensive intelligence framework necessary to navigate the period ahead with confidence.
For detailed analysis of this topic, please visit the official page: DNA Microarray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Checkweighers Reach $397.5M in 2025, Projected to Hit $539.0M by 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Automatic Checkweighers Market: Navigating Growth Through Precision and Compliance
Executive Overview
In the modern manufacturing and packaging landscape, the automatic checkweigher has evolved from a simple weight verification tool into a critical node within quality assurance ecosystems. As regulatory frameworks tighten and consumer expectations for product consistency rise, the strategic deployment of these systems determines operational efficiency and brand integrity. This article examines the trajectory of the global Automatic Checkweighers Market, highlighting why robust intelligence is essential for decision-makers navigating the period from 2026 through 2032.
Understanding the macroeconomic indicators is the first step, but true competitive advantage lies in decoding the underlying drivers. Our latest research publication dissects these complexities to provide a roadmap for capital allocation, technology adoption, and supply chain optimization. The following analysis outlines the market structure, competitive intensity, and regulatory currents that define this sector, underscoring the necessity of detailed data for precise strategic planning.
Market Trajectory and Economic Foundations
The industry has demonstrated resilience and steady expansion over the past half-decade. Historical data indicates a consistent upward trend, with the market valuation rising from approximately 320.0 million USD in 2020 to an estimated 397.5 million USD by 2025. This historical performance sets a robust baseline for the forecast period. Looking forward, the market is projected to grow from 423.84 million USD in 2026 to 539.0 million USD by 2032.
This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.5% during the forecast window. While these aggregate figures provide a high-level view of health, they merely scratch the surface of the available intelligence. The value for enterprise strategists lies not in the total number, but in understanding which specific segments are driving this velocity. The report delves into breakouts that reveal where investment yields the highest returns, without exposing the granular percentages publicly. Decision-makers require knowledge of which specific types or applications are outpacing the average growth rate to prioritize their procurement strategies effectively.
Furthermore, the concentration of market power is a critical consideration. With the top three players holding a significant share and the top five commanding an even larger portion of the revenue, the market structure suggests a competitive environment where differentiation is key. Understanding the dominance of these key entities helps purchasers evaluate vendor stability and negotiate terms, while vendors themselves need to know the barriers to entry and the space available for mid-tier players to capture niche opportunities.
Segmentation Dynamics and Strategic Allocation
Effective market strategy requires a nuanced understanding of how demand is distributed across different categories. The landscape is primarily segmented by region, type, and application, each presenting distinct challenges and opportunities for stakeholders. While aggregate revenue is important, the allocation of resources across these dimensions determines the success of implementation.
Regarding regional distribution, North America and Europe have historically maintained substantial presence, reflecting mature industrial bases and stringent regulatory environments. However, the Asia Pacific region presents a compelling growth narrative driven by expanding manufacturing capabilities and increasing adoption of automation technologies. Latin America and the Middle East and Africa, while smaller in current valuation, represent emerging avenues for expansion. Our analysis breaks down the revenue contribution of each geography to identify where infrastructure development is accelerating demand for inline quality control solutions.
In terms of technology type, the market is divided among In-Motion, Static, and Combination systems. In-Motion checkweighers dominate the revenue landscape, catering to high-speed production lines where downtime is costly. Static systems serve specific applications requiring precise stationary weighing, while Combination systems offer integrated solutions that merge checkweighing with metal detection or other inspection technologies. The choice between these types depends heavily on the production speed and the specific quality control requirements of the facility. The report provides detailed assessments of the revenue split between these types to guide equipment selection based on operational throughput needs.
Application-wise, the Food and Beverage sector remains the primary driver of demand, accounting for the largest share of revenue. This is followed by the Pharmaceutical industry, which demands higher accuracy and compliance standards, along with Consumer Products and other sectors. Each application vertical imposes unique requirements on checkweigher specifications, such as hygienic design for food or data integrity for pharma. By analyzing the revenue distribution across these applications, companies can tailor their marketing efforts and product development roadmaps to the most lucrative verticals. For instance, the pharmaceutical segment may offer lower volume but higher margin potential compared to high-volume food processing.
Strategic Segments Covered in the Full Report:
- By Region: Detailed revenue analysis for North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- By Type: In-depth evaluation of In-Motion, Static, and Combination checkweigher systems.
- By Application: Comprehensive breakdown of Food and Beverage, Pharmaceutical, Consumer Products, and Other sectors.
Competitive Landscape and Key Player Strategies
The market is characterized by the presence of established multinational corporations and specialized manufacturers who compete on precision, integration capabilities, and compliance certifications. The competitive intensity is high, with consolidation trends and strategic partnerships shaping the industry structure. Major players are not only competing on hardware specifications but also on software integration and after-sales support ecosystems.
Automatic Checkweighers Market
Mettler-Toledo International Inc., headquartered in Switzerland, continues to be a dominant force, particularly known for their C-Series and PlusLine dynamic checkweighers. Their strategy heavily emphasizes MID certification and seamless integration with metal detectors and X-ray systems, specifically targeting food packaging quality control. Recent activities, such as their demonstration of C33 PlusLine checkweighers and CM/CX combination systems at Anuga FoodTec 2025, highlight their commitment to enhancing inspection capabilities through integrated solutions.
Ishida Co., Ltd., based in Kyoto, Japan, competes with high-speed multi-lane capabilities through their DACS-GN and DACS-EL series. Their focus on MID approval ensures compliance for the European market, making them a strong candidate for global manufacturers operating under strict regulatory regimes. Similarly, Wipotec-OCS GmbH from Germany offers HC-A and HC-M dynamic checkweighers optimized for high-throughput food and industrial applications. Their March 2026 catalog release emphasizing modular integration for shipping cases underlines their focus on flexibility and logistics efficiency.
Other significant contributors include Anritsu Corporation, whose SSV-h series utilizes force-balance load cells for high accuracy in pharma and food industries, ensuring reliability in sensitive environments. Bizerba SE & Co. KG and Yamato Scale Co., Ltd. provide integrated solutions that blend checkweighing with metal detection and multihead weighing, respectively, catering to snack packaging and high-speed pharmaceutical lines. Minebea Intec GmbH rounds out the European presence with their Essentus performance series, focusing on combination systems for pharma and food safety. Loma Systems, based in the UK, reinforces the importance of compliance with their CW3 dynamic checkweighers, often exhibited alongside metal detection and X-ray solutions at events like Pack Expo East 2026.
Additionally, A&D Company, Limited and Thermo Fisher Scientific Inc. contribute to the ecosystem with high-precision industrial checkweighers and IoT-enabled static and dynamic systems. The presence of Thermo Fisher Scientific highlights a trend toward connectivity and data monitoring in pharmaceutical applications. The report provides a detailed competitive benchmarking of these ten key companies, analyzing their market share, product portfolios, and strategic moves to help stakeholders identify potential partners or competitors.
Regulatory Pressures and Industry Dynamics
Compliance is no longer optional; it is a primary driver of technology adoption. Regulatory mandates such as the Weights and Measures Act and various food safety standards require manufacturers to implement precise weighing solutions to prevent underfilling or overfilling. This regulatory pressure directly fuels demand for MID-certified devices and systems that can log data for audit trails.
Manufacturers are increasingly seeking solutions that offer inline quality control checks while helping them meet compliance requirements without slowing down production lines. For instance, the requirement for Measuring Instruments Directive approval in Europe influences procurement decisions for companies exporting to the EU. The integration of checkweighers with metal detectors and X-ray systems is also becoming standard practice to ensure comprehensive safety compliance, particularly in the food sector.
Recent industry developments underscore this focus on compliance and integration. Mettler-Toledo's emphasis on MID-certified dynamic checkweighers at trade shows demonstrates how vendors are aligning their product launches with regulatory needs. Similarly, Ishida's incorporation of MID approval in their DACS-GN series and Wipotec's support for high-speed applications with precision weighing technology meeting industry standards reflect a broader industry shift. Anritsu's SSV-h series meeting stringent accuracy standards and Loma Systems' design for food safety compliance further illustrate how regulation shapes product specifications. These dynamics suggest that vendors who can certify their equipment and simplify compliance reporting will gain a competitive edge in the coming years.
Strategic Implications for 2026 Decision-Makers
For executives and procurement leaders, the 2026 landscape demands a shift from reactive purchasing to proactive strategic planning. The data indicates that while the market is growing steadily, the value lies in selecting the right technology for the right application. Investing in static systems for high-speed lines may result in bottlenecks, whereas in-motion systems might be overkill for low-volume pharmaceutical batches.
Companies must also consider the total cost of ownership, including integration costs with existing sensors and control systems. The trend toward combination systems suggests that future-proofing facilities with modular equipment that can add metal detection or X-ray capabilities later is a prudent strategy. Furthermore, the geographic shifts in demand imply that supply chain logistics and local service support are critical factors when selecting vendors. Manufacturers operating globally need to ensure their partners have a presence and certification status relevant to their operating regions.
The concentration of the market also implies that negotiating leverage may vary depending on the vendor. Smaller players might offer more customized solutions or faster support, while larger incumbents provide stability and a broader portfolio. Understanding the specific market share and positioning of the top key companies allows businesses to benchmark their current vendors and explore alternatives that might offer better value or technological alignment.
Checkweighers Market
Conclusion and Call to Action
The Automatic Checkweighers Market is poised for steady expansion, driven by regulatory compliance, quality assurance demands, and industrial automation trends. However, navigating this landscape requires more than high-level growth rates. It demands a granular understanding of regional revenue splits, segmentation performance, and competitive maneuvering.
This article has highlighted the key themes and dynamics shaping the industry, but the full strategic picture requires access to comprehensive data. To unlock the complete intelligence necessary for informed decision-making, including detailed segmentation splits, historical data tables, and exhaustive competitor profiling, we invite you to access the full market research report. Equip your organization with the precise data needed to optimize investments and stay ahead in a competitive manufacturing environment.
Access the Full Automatic Checkweighers Market Report Here
For detailed analysis of this topic, please visit the official page: Automatic Checkweighers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vein Finder Market to Hit $574M by 2032, Driven by 5.15% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Wave of Growth: Strategic Insights into the Global Vein Finder Market
The global healthcare landscape is undergoing a profound transformation, driven by an aging population, a rising prevalence of chronic diseases, and an unwavering commitment to improving patient safety and clinical outcomes. Within this complex ecosystem, the Vein Finder Market has emerged as a critical niche, bridging the gap between advanced optical technology and everyday clinical necessity. For business leaders, investors, and strategic planners operating in the medical device sector, understanding the trajectory of this market is no longer optional—it is imperative. Our latest comprehensive study on the Vein Finder Market offers a detailed roadmap for navigating the competitive and regulatory complexities of the next decade, with a specific focus on positioning for success in 2026 and beyond.
This report serves as a strategic compass, designed to cut through market noise and provide actionable intelligence. By analyzing historical performance from 2020 through 2025 and projecting trends through 2032, we provide a granular view of how near-infrared technology, transillumination devices, and innovative imaging solutions are reshaping vascular access and dermatological procedures. The following analysis highlights the core value propositions of this research, illustrating why timely access to deep market intelligence is the key differentiator for organizations aiming to capitalize on the projected revenue growth of the industry.
Market Trajectory and Financial Outlook
The financial architecture of the vein finder industry demonstrates robust resilience and steady expansion. Based on extensive historical data and forward-looking modeling, the market has shown consistent momentum over the past half-decade. Starting from a base of approximately 312.45 million USD in 2020, the industry has navigated various economic and supply chain challenges to reach a valuation of 405.0 million USD by 2025. This upward trajectory underscores the growing adoption of vein visualization technologies across diverse healthcare settings, from large hospital networks to specialized outpatient clinics.
Looking ahead, our forecasts indicate that this growth will not only continue but accelerate in specific segments. The market is projected to surpass the 418 million USD mark in 2026, driven by renewed demand for precision medical tools and the integration of advanced imaging capabilities into standard care protocols. As we extend our horizon to 2032, the cumulative growth potential becomes even more significant, with revenue streams expected to expand substantially as technology becomes more accessible and regulatory pathways clear for innovative entrants. The Compound Annual Growth Rate (CAGR) analyzed over the forecast period reflects a healthy expansion rate that suggests sustained investor interest and robust commercial opportunities for manufacturers and distributors alike.
For strategic decision-makers, these figures represent more than just abstract numbers; they reflect shifting procurement priorities and the increasing allocation of capital toward technologies that reduce procedure times and enhance patient comfort. Understanding the scale of this opportunity is the first step in formulating a market entry or expansion strategy that aligns with global healthcare trends.
Segmentation Strategy and Product Diversity
A critical component of our analysis delves into the structural composition of the market, offering a clear view of how different product types and applications drive revenue. The industry is not monolithic; it is segmented by technology type, application area, and regional deployment, each with unique drivers and constraints. Our report dissects these segments to reveal where value is being created and where competitive intensity is highest.
On the product front, the landscape is dominated by a mix of portable and stationary solutions. Handheld vein finders continue to hold a significant share of the market, appealing to clinicians who prioritize mobility and rapid deployment in various settings, including emergency rooms and home healthcare. Stationary systems, meanwhile, are finding strong footholds in specialized procedural rooms where integration with other monitoring equipment is essential. Additionally, emerging categories within the product mix are beginning to capture niche demands, reflecting the industry's evolution toward specialized imaging solutions. Understanding the revenue contribution and growth rate of each product category is vital for companies deciding whether to focus on mass-market portability or high-end stationary integration.
Similarly, the application landscape is diverse. Vascular access procedures remain the cornerstone of demand, driven by the sheer volume of intravenous cannulations, blood draws, and infusion therapies performed globally. However, dermatology procedures represent a growing avenue for vein finders, as practitioners leverage these tools for cosmetic assessments, sclerotherapy planning, and diagnostic imaging. By analyzing the revenue distribution across these application areas without limiting the view to superficial percentages, our report helps stakeholders identify high-growth niches that may offer better margins or lower competitive saturation.
Vein Finder Market
Competitive Arena and Key Player Dynamics
The competitive environment in the vein finder market is characterized by a mix of established innovators and emerging challengers, creating a dynamic landscape where differentiation is key to survival. Our research provides deep-dive profiles on the companies that are shaping the industry, analyzing their product pipelines, strategic positioning, and recent corporate activities.
Leading the charge in North America, AccuVein Inc., based in Medford, NY, continues to set benchmarks with its near-infrared vein visualization devices. The company's focus on improving imaging quality and field durability was recently highlighted by the launch of the AccuVein AV600, a fourth-generation handheld system introduced to US customers in April 2026. This product launch underscores the company's commitment to iterative innovation and maintaining a strong foothold in the premium segment of the market. Similarly, Christie Medical Holdings, Inc. remains a formidable presence with its VeinViewer series, including the VeinViewer Flex. Their devices are widely recognized for their reliability in hospital environments, and their user guides emphasize strict compatibility with cleaning solutions, reflecting the growing importance of infection control standards in device design and procurement.
The competitive field also includes specialized manufacturers like TransLite LLC, known for its Veinlite transillumination devices such as the EMS PRO models, which cater to specific procedural needs with proven transillumination technology. On the global stage, manufacturers from Asia are increasingly influencing the market dynamics. Qualmedi Technology Co., Ltd. from China has been active in updating its product catalog with details on portable near-infrared vein finders like the QV-500 and QV-600 models, signaling a focus on expanding its footprint in portable imaging solutions. Meanwhile, ZD Medical Inc. is positioning itself as a supplier of new-generation near-infrared vein finder systems, aiming to capture demand for cost-effective yet advanced imaging tools.
Worldwide LED Vein Finders Market
Recent developments highlight the pace of innovation and regulatory navigation within the sector. In a notable move for the Indian market, Polymatech achieved a milestone in January 2026 by pioneering the first CDSCO-registered indigenous near-infrared LED vein finder device. This achievement not only validates the technological capability of local manufacturers but also aligns with broader regulatory trends favoring indigenous medical device production and compliance with national medical device rules. Such developments are critical indicators of how market access strategies are evolving, particularly in regions where regulatory clearance can serve as both a barrier and a catalyst for growth.
Industry Dynamics and Regulatory Landscape
Navigating the vein finder market requires a keen understanding of the regulatory environment, which varies significantly by region and device classification. Our report integrates essential regulatory context to help stakeholders anticipate compliance requirements and market access challenges. In the United States, many non-contact projection vein visualization systems, including devices like the NextVein V800NV, are classified as Class 1 510(k) exempt devices. This classification streamlines the pathway for market entry for certain low-risk devices, potentially encouraging a higher volume of product launches and competing offerings. However, companies must remain vigilant, as regulatory classifications can shift, and adherence to labeling and usage guidelines remains critical for liability and safety assurance.
Infection control and device compatibility are also becoming central themes in market dynamics. As hospitals and healthcare facilities enforce stricter hygiene protocols, manufacturers are responding by ensuring their devices are compatible with specific cleaning solutions and durable enough to withstand rigorous sanitation processes. Christie Medical Holdings' emphasis on cleaning solution compatibility in their VeinViewer Flex user guide is a prime example of how operational guidelines are adapting to post-pandemic healthcare realities. Furthermore, in markets like India, compliance with frameworks such as the Medical Devices Rules 2017 is essential for registration and commercial viability, as demonstrated by Polymatech's successful CDSCO registration. These regulatory nuances are meticulously detailed in our study, providing a checklist for companies evaluating expansion into new geographies or launching new product lines.
Strategic Value for 2026 Decision-Making
Why does this level of detail matter for your organization's 2026 strategy? The medical device market is increasingly data-driven, and decisions based on surface-level information carry significant risk. Our Vein Finder Market research report is designed to mitigate that risk by providing a holistic view of the ecosystem. Whether you are a manufacturer looking to refine your product roadmap, a distributor assessing potential partners, or an investor evaluating the viability of a portfolio company, the insights contained in this report are tailored to support high-stakes decision-making.
The report goes beyond historical data to explore the catalysts that will define the next growth cycle. It examines how technological advancements in near-infrared imaging, miniaturization, and user interface design are influencing purchasing decisions. It analyzes the competitive pressure points, such as pricing strategies, patent landscapes, and regional manufacturing capabilities. By understanding the concentration of market share among top players and the fragmentation in other segments, you can better position your organization to capture market share or defend existing revenues.
Moreover, the analysis of regional dynamics provides context for where demand is originating and where infrastructure is developing. While global totals provide the macro view, understanding the flow of capital and adoption rates across different healthcare systems is essential for resource allocation. Our report synthesizes these factors to offer a clear picture of opportunities that are ripe for investment or expansion in the coming year.
Unlock the Full Intelligence
The vein finder industry is at an inflection point where technology, regulation, and clinical demand are converging to create substantial opportunities. However, capitalizing on these opportunities requires more than a general understanding of market trends; it demands precise, actionable intelligence that is grounded in rigorous analysis and up-to-date data. This overview has touched upon the breadth of the market, the key players, and the regulatory currents shaping the industry, but it represents only a fraction of the detailed intelligence available in our full report.
To fully equip your organization for strategic planning in 2026 and the forecast period through 2032, we invite you to access the complete Vein Finder Market research study. The full report contains comprehensive segmentation data, detailed financial models, in-depth competitor profiling, and specific regional analyses that are essential for crafting a winning strategy. Do not navigate the future of this market with partial information. Explore the complete findings to gain the competitive edge needed to thrive in a dynamic and rapidly evolving healthcare technology landscape. Visit our source page to download the full intelligence and secure your strategic advantage today.
The path forward is clear for those who have the right data. Let our research be the foundation of your next strategic move.
For detailed analysis of this topic, please visit the official page: Vein Finder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global Petrochemicals Market is entering a transformative era of structural realignment, according to a comprehensive intelligence study released by Stellar Market Research . Valued at USD 566.54 billion in 2025, the market is projected to surge to nearly USD 872.88 billion by 2034 , registering a compound annual growth rate (CAGR) of 4.92% over the forecast period. This robust expansion underlines the critical strategic importance of petrochemicals as the primary engine for global crude oil demand growth through the next decade.
Key Findings from the Report:
-
Market Valuation: The global petrochemicals market was valued at USD 566.54 billion in 2025 and is on track to reach USD 872.88 billion by 2034.
-
Growth Trajectory: The industry is forecast to expand at a steady CAGR of 4.92% from 2026 to 2034.
-
Segment Dominance: The Aromatics segment dominated global revenues in 2025, led by ethylene consumption as a core building block for plastics and industrial chemicals.
-
Regional Leadership: Asia Pacific commanded over 45% of the total revenue share in 2025, anchored by rapid industrialization and escalating domestic demand.
-
High-Growth Region: North America secured the second-largest market share in 2025 and is projected to expand at a robust CAGR of 6.62% through the forecast period.
-
Demand Driver: Rising consumption of consumer staples and packaging materials countered temporary durable goods slumps, fueling a strong volume rebound in the second half of 2025.
-
Investment Relevance: Heightened demand growth potential compared to conventional transportation fuels is accelerating joint ventures and vertical integrations between major oil corporations and chemical refiners.
For further information, click the following link: https://www.stellarmr.com/report/req_sample/Petrochemicals-Market/290
Market Drivers and Restraints:
-
Driver 1: Surging Plastics and Polymer Demand in Emerging Economies: Rapid urbanization and rising disposable incomes across developing nations are accelerating the adoption of everyday consumer goods, packaging, and automotive components, creating relentless downstream demand for base petrochemicals.
-
Driver 2: Integration of Refining and Petrochemical Assets: Refiners are strategically combining operations to pivot away from declining fuel markets, capitalizing on the superior demand-growth rate of petrochemicals (2% to 3% annually) compared to transportation fuels (<1% annually).
-
Driver 3: Feedstock Diversification: The expansion of natural gas liquids (NGLs) and non-oil feedstocks provides producers with flexible, cost-effective pathways to maintain production margins amid crude price volatility.
-
Restraint 1: Feedstock Cost and Price Volatility: Fluctuations in Brent crude and natural gas prices directly impact regional cost curves, squeezing operational margins for players dependent on traditional raw materials.
-
Restraint 2: Stringent Environmental Regulations & Project Delays: Heightened global scrutiny over carbon emissions and plastic waste, coupled with localized regulatory hurdles, frequently causes capital expenditure delays and forces costly compliance overhauls.
Technology, Regulation, and Sustainability Trends: The petrochemical industry is undergoing a monumental operational transformation driven by environmental, social, and governance (ESG) imperatives. Producers are heavily investing in circular economy initiatives, such as advanced chemical recycling technologies, to convert plastic waste back into pyrolysis oil feedstocks. Simultaneously, stringent decarbonization mandates are pushing operators to adopt energy-efficient cracking furnaces, carbon capture, utilization, and storage (CCUS) systems, and green hydrogen integration. Regulatory compliance is no longer a peripheral concern; it is a core operational framework shaping long-term capital allocation, facility localization, and licensing approvals worldwide.
Regional Insights:
-
Asia Pacific: Dominating the global landscape with over 45% revenue share in 2025, Asia Pacific continues to experience rapid expansion. Surging manufacturing output, massive domestic infrastructure projects, and aggressive capacity additions in China, India, and Southeast Asia are cementing the region's status as the epicenter of petrochemical consumption.
-
North America: Holding the second-largest revenue share, North America is poised for significant acceleration at a 6.62% CAGR. Growth is heavily supported by the ethylene segment, driven by high utilization rates in automotive anti-freeze/cooling systems and booming demand from the packaged food and cold-chain logistics sectors.
Recent Industry Developments:
-
ExxonMobil (2025): Commissioned advanced chemical recycling facilities to scale up circular plastics production, successfully diverting post-use plastics from landfills and lowering lifecycle carbon intensity.
-
SABIC (2025): Partnered with key engineering firms to deploy low-carbon electrical steam cracking technology, targeting a substantial reduction in Scope 1 emissions across core petrochemical hubs.
-
INEOS Group Ltd. (2025): Finalized major investments in European asset optimization, securing diversified alternative feedstocks to hedge against regional energy supply volatility.
-
Reliance Industries (2026): Announced strategic expansions in its downstream polyester and ethylene derivatives value chain to cater to surging domestic packaging and textile demands in South Asia.
-
ADNOC (2026): Accelerated multi-billion-dollar investments in integrated refining-petrochemical complexes, enhancing chemical conversion rates from crude oil to future-proof its downstream portfolio.
Competitive Landscape: The global petrochemicals market is characterized by high capital intensity and consolidation among state-owned enterprises and multinational conglomerates. Key players—including Exxon Mobil Corporation, China Petrochemical Corporation (SINOPEC), China National Petroleum Corporation (CNPC), SABIC, INEOS Group Ltd., Royal Dutch Shell, BP PLC, Reliance Industries, Chevron Corporation, and Abu Dhabi National Oil Company (ADNOC)—are actively focusing on strategic mergers, vertical integration, and joint ventures. Leading operators are prioritizing geographic expansion into high-growth emerging markets while allocating substantial R&D capital toward low-carbon technologies and bio-based chemical alternatives to secure a competitive moat.
Analyst Commentary:
"The petrochemical sector is navigating a defining strategic crossroads where traditional volume-driven models must seamlessly merge with aggressive decarbonization and feedstock agility," said a Senior Research Analyst at Stellar Market Research . "As oil corporations increasingly look to chemicals to buffer against slowing transportation fuel demand, the winners of the next decade will be those who successfully leverage advanced process technologies, circular recycling frameworks, and localized feedstock optimization to protect margins in a shifting regulatory landscape."
Future Outlook: Through 2034, the global petrochemicals market is anticipated to evolve through disciplined capacity expansion, digital plant optimization, and rigorous ESG alignment. While feedstock constraints in traditional regions like North America and the Middle East will mature, rising demand for specialty polymers, green plastics, and advanced industrial intermediates will sustain healthy market growth. Long-term capital investments will increasingly favor sustainable assets, ensuring that petrochemicals remain an indispensable pillar of the modern global economy.
For further information, click the following link: https://www.stellarmr.com/report/req_sample/Petrochemicals-Market/290
About Stellar Market Research
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656
PW Consulting: Chromium Oxide Green Market Hits $546.5M in 2025, Projects 5.2% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Chromium Oxide Green Market: Navigating Growth, Regulation, and Competitive Shifts in 2026
The global Chromium Oxide Green market stands at a critical inflection point. As we move deeper into 2026, corporate procurement leaders, specialty chemicals strategists, and materials procurement directors face a dual mandate: secure resilient supply chains for this essential inorganic pigment while navigating accelerating regulatory constraints and structural cost realignment across the value chain. Our latest Chromium Oxide Green Market research report has been engineered specifically to equip decision-makers with the granular, actionable intelligence required to transform these macroeconomic currents into competitive advantage.
The 2026 Inflection Point: Why Foundational Commodity Intelligence Must Be Upgraded
Market trajectories in specialty inorganic colorants and refractory oxides rarely move in straight lines. They are shaped by energy arbitrage, raw-material feedstock dynamics, stringent environmental compliance regimes, and the strategic positioning of a concentrated global supplier base. Between 2020 and 2025, the global Chromium Oxide Green market demonstrated consistent upward momentum, expanding from approximately 430.15 million USD to 546.5 million USD. Looking forward, our forecast models project a compound annual growth rate of 5.2 percent across the 2026 to 2032 horizon, with market valuation expected to reach 583.38 million USD this year and continue climbing toward 776.2 million USD by 2032.
These headline figures tell only the opening chapter. The real strategic challenge lies beneath the surface: understanding where growth is actually concentrating, which grades are experiencing margin compression or expansion, how regional supply architectures are shifting under regulatory and energy-cost pressures, and how major players are recalibrating their portfolios in response to rising compliance expenditures. Our research converts historical data into forward-looking intelligence, giving stakeholders the analytical scaffolding to anticipate disruption rather than simply react to it.
Decoding the Report Structure: Actionable Intelligence, Not Just Market Commentary
To be useful at the executive level, a market study must bridge financial overview and operational reality. This report is deliberately structured to deliver both, providing a comprehensive yet operationally grounded view of the Chromium Oxide Green landscape.
Macroeconomic Baseline and Forecast Architecture
The analysis anchors itself on verified historical performance data spanning 2020 through 2025, then extends a rigorously modeled forecast through 2032. Readers will gain visibility into total revenue progression, year-over-year growth inflection points, and the underlying assumptions driving the 5.2 percent CAGR trajectory. Crucially, the report contextualizes how macroeconomic variables—including energy pricing volatility, logistics cost escalation, and shifting end-market demand intensities—interact with each forecast year. The analysis is designed for scenario planning: procurement teams can stress-test budget assumptions, while commercial leaders can evaluate whether their current pricing and volume strategies will hold through the latter half of the decade.
Segmentation Deep Dive: Type, Application, and Regional Dynamics
Market value rarely distributes evenly across grades, downstream uses, or geographies. The report systematically deconstructs the Chromium Oxide Green market across three foundational axes. By type, the analysis distinguishes performance and pricing dynamics between pigment-grade material, metallurgical-grade chromium oxide, and refractory-grade applications. Each grade follows fundamentally different demand drivers, margin structures, and competitiveness criteria, and our segmentation framework unpacks how these categories interact with end-user procurement cycles.
By application, the study traces how downstream industries consume Chromium Oxide Green, evaluating which sectors anchor baseline demand and where growth pockets are emerging. By region, the analysis maps geographic value distribution, supply concentration patterns, and localized regulatory or cost pressures. Rather than presenting static share tables, the report synthesizes regional and segmentation data into strategic narratives: where supply is tightening, where overcapacity risks are building, and where buyers must prioritize supplier diversification to avoid exposure.
Competitive Landscape and Supplier Positioning
Understanding who controls the market is essential for both buyers and new entrants. The report profiles the core companies that define the Chromium Oxide Green competitive arena, evaluating their geographic footprint, grade specializations, production capabilities, and strategic priorities. The landscape features a mixture of global specialty chemical leaders, regional pigment specialists, and cost-competitive producers operating across Europe, North America, Asia Pacific, and Central Asia.
Key corporate profiles are analyzed, including LANXESS, which produces Chromium Oxide Green inorganic pigments at its Krefeld-Uerdingen site and maintains a position as a leading global supplier focused on high-purity grades and eco-aligned production; Elementis, a major European producer with strength in high-purity and metallurgical-grade material; Venator, whose pigment lines serve coatings, plastics, and refractory applications with an emphasis on sustainable product portfolios; Vishnu Chemicals, an Indian manufacturer offering high-purity 99 percent Cr2O3 grades for refractories, ceramics, and chromium metal production; and Hunter Chemical LLC, which supplies multiple PG17 grades for coatings, thermoplastics, refractories, and building materials, including an FDA-approved portfolio. The competitive mapping also includes distribution and market access players such as Cofermin Chemicals, which has distributed LANXESS pigments across niche and global markets since 2009, and industrial chemical giants such as Huntsman Corporation, whose Titanium Dioxide and Specialty Products divisions maintain a sustainability-focused pigment offering.
The analysis further tracks how Chinese producers, including Hubei Zhenhua Chemical, Hebei Chromate Chemical, and Jirong Chemical, compete on cost structures and export positioning, alongside regional producers including Aktyubinsk in Kazakhstan and MidUral Group in Russia, which maintain active roles in metallurgical and refractory segments. The competitive section does not merely list capabilities; it interprets how each participant’s positioning affects supply security, pricing leverage, and negotiation dynamics for downstream buyers.
Worldwide Chromium Salt Market
Industry Dynamics Reshaping the Chromium Oxide Green Competitive Arena
A forecast number without context is a liability. The report integrates the operational and regulatory forces that are actively reshaping procurement conditions, production economics, and supplier viability in 2026 and beyond.
Regulatory Pressure and the Compliance Cost Curve
The regulatory environment for chromium compounds continues to tighten globally. Hexavalent chromium usage faces mounting restrictions, and approximately 52 percent of manufacturers globally are reporting increased compliance costs as a result. At the same time, environmental restrictions on chromium compounds are affecting roughly 48 percent of production facilities through strict emission standards. These are not peripheral concerns; they directly influence which facilities can expand, which suppliers remain viable in high-regulation jurisdictions, and how compliance overhead flows through pricing structures.
On the registration side, REACH registration requirements apply to Chromium(III) oxide (CAS 1308-38-9), with safety data sheets updated as recently as August 2025. For companies operating across European supply chains or selling into markets that reference REACH-aligned standards, maintaining current documentation and compliance readiness is an active operational requirement, not a one-time administrative task. The report helps procurement and regulatory teams understand where documentation risk concentrates and how compliance readiness affects supplier qualification.
Chromium Oxide Green Market
Feedstock Dependency, Capacity Foundations, and Pricing Signals
Chromium Oxide Green production relies on sodium dichromate as the primary feedstock, and the stability of that input chain directly affects cost predictability across pigment, metallurgical, and refractory lines. Production capacity globally is estimated at approximately 88,500 tonnes per year, supporting both refractory and pigment segment demand. While no specific transport surcharges have been identified for the feedstock at this time, broader logistics and energy cost movements still exert pressure on delivered economics.
These structural realities are already translating into market-moving pricing actions. In March 2026, LANXESS announced a price increase for inorganic pigments including Chromium Oxide Green of up to 20 percent effective immediately, citing higher energy, raw material, and logistics costs. This is a telling signal for the broader market: when leading global suppliers adjust pricing on this scale, downstream buyers quickly see how cost inflation propagates through grade portfolios and contract structures. The report contextualizes this and other recent developments so that procurement teams can distinguish between temporary cost shocks and structural repricing trends.
What This Means for Strategic Decision-Making in 2026
For corporate buyers, the immediate implications are practical and urgent. Supplier diversification strategies must account for regulatory exposure, energy-cost vulnerability, and grade-specific supply reliability. Contract negotiations must factor in compliance-driven cost trajectories rather than assuming baseline stability. Procurement teams evaluating refractory or pigment-grade requirements need to understand not just current pricing, but how feedstock dependencies and regional concentration patterns will shape availability and bargaining power over the next several years.
For investors and market entrants, the analysis clarifies where value pools are forming, which grade segments are most sensitive to raw-material volatility, and how competitive intensity differs across geographies and applications. For product and operations leaders, the report provides the baseline needed to assess whether existing supplier relationships, inventory strategies, and compliance readiness align with the market’s new cost and regulatory architecture.
Why This Research Matters Now
The Chromium Oxide Green market is not static. It is being reshaped by overlapping forces that will define procurement economics, supplier viability, and growth opportunity through 2032. This report is designed to give decision-makers a clear, evidence-based view of those forces without obscuring the complexity that matters most. It connects historical performance to forward forecasts, translates segmentation structure into commercial strategy, and situates competitive dynamics within a regulatory and cost environment that is already in motion.
For leaders who need to move beyond headline market size and understand how Chromium Oxide Green supply, pricing, and competitive positioning will actually behave in their specific operating context, the full study provides the depth required to act with confidence. The complete dataset, detailed segmentation analysis, supplier-by-supplier strategic evaluation, and operational scenario frameworks are available in the full report. Access the complete Chromium Oxide Green Market research to equip your 2026 and beyond decisions with intelligence built for execution.
For detailed analysis of this topic, please visit the official page: Chromium Oxide Green Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ride Sharing Market Hits $47.22B in 2025, Projects 5.85% CAGR to $69.79B by 2032
By PW Consulting, 2026-09-16
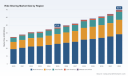
Strategic Horizons in the Ride Sharing Market: A 2026 Decision-Maker’s Guide to Sustainable Mobility Growth
The global ride sharing ecosystem has evolved from a disruptive novelty into a foundational pillar of modern urban and interurban mobility. As enterprises, municipalities, and mobility operators navigate an era defined by regulatory realignment, autonomous technology maturation, and shifting consumer expectations, the need for precise, forward-looking intelligence has never been more acute. PW Consulting’s newly released ride sharing market research delivers exactly that: a comprehensive, data-grounded examination of an industry poised for sustained expansion through the end of the decade. This introduction outlines the strategic architecture of the study, highlights the macro-level trajectory shaping 2026 corporate planning, and demonstrates how decision-makers can translate analytical depth into actionable competitive advantage.
The Macro Trajectory: Mapping an Industry in Deterministic Expansion
Over the past half-decade, the global ride sharing sector has demonstrated remarkable resilience and consistent upward momentum. Historical valuation data from 2020 through 2025 reveals a market that has systematically outpaced pre-pandemic projections, recovering swiftly from operational disruptions and reinvesting in platform sophistication, fleet modernization, and geographic penetration. The baseline valuation has climbed steadily across successive fiscal periods, establishing a robust foundation for the current forecast cycle.
Looking ahead, our modeling frameworks project a compound annual growth rate of approximately 5.85% across the 2026 to 2032 horizon. This trajectory reflects a confluence of structural drivers: urbanization intensification, the normalization of app-based mobility as a primary transit alternative, and the gradual integration of alternative powertrains into commercial fleets. By the close of the forecast window, the sector is positioned to surpass significant valuation thresholds, reshaping how capital is allocated, how partnerships are structured, and how regulatory compliance is priced into operational models. For executives evaluating market entry, portfolio diversification, or technology investments, these macro indicators provide a reliable compass—but they represent only the starting point. The real strategic differentiation lies beneath the headline figures.
Beyond Headline Numbers: What the Report Delivers for 2026 Strategy
PW Consulting’s research framework is engineered for practitioners who require more than aggregate market sizing. The study dissects the ride sharing value chain through multiple analytical lenses, ensuring that strategic, financial, and operational leaders can extract precise insights tailored to their functional mandates. Rather than presenting static snapshots, the report maps intercurrent dynamics—how pricing architectures interact with regional regulatory environments, how service-tier positioning influences customer retention, and how application-specific demand patterns reshape fleet deployment strategies.
The analytical architecture encompasses detailed breakdowns of market structure across geographic territories, service classifications, and utilization contexts. Each segmentation is examined not in isolation, but as part of an interconnected ecosystem where cross-regional demand shifts, tiered pricing elasticity, and destination-driven utilization patterns collectively inform competitive positioning. Additionally, the study evaluates market concentration dynamics, highlighting how dominant platform architectures shape pricing power, network effects, and barriers to entry. For strategy teams, this means moving beyond speculative trend-chasing toward evidence-based scenario planning that accounts for both near-term operational realities and long-term structural shifts.
Competitive Architecture: Navigating a Consolidated but Dynamic Landscape
The ride sharing sector remains characterized by pronounced concentration, with a small cohort of globally scaled platforms commanding the majority of market share. This consolidation has not eliminated competitive friction; rather, it has elevated the complexity of differentiation. Market leaders must balance scale economies with localized service quality, regulatory adaptability, and technological innovation, while emerging and regional players pursue niche positioning, transparent pricing models, and multi-modal service integration.
Carpooling Market
The report provides granular corporate profiling for pivotal industry participants, examining their operational footprints, strategic priorities, and recent market maneuvers. Uber Technologies, Inc. continues to anchor the global landscape through its expansive network architecture and deepening integration with public-sector mobility procurement, including recently formalized government-wide ride procurement frameworks that extend its footprint into federal civilian and defense ecosystems. Lyft, Inc. has reinforced its North American operational base through sustained platform expansion and capital allocation strategies that signal confidence in long-term urban mobility demand.
Ride Sharing Market
In parallel, regional and specialized operators are redefining competitive boundaries. Bolt Technology OÜ maintains aggressive multi-country expansion, leveraging localized driver incentives and streamlined urban routing. Grab Holdings Limited has entrenched itself as a comprehensive Southeast Asian mobility and services ecosystem, blending ride sharing with adjacent consumer platforms to drive retention and cross-utilization. inDriver has carved a distinct positioning around transparent, user-negotiated pricing and driver-centric earnings structures, appealing to cost-sensitive urban demographics. Via Transportation, Inc. continues to pioneer on-demand microtransit and optimized ride-pooling architectures, addressing gaps in scheduled public transit and suburban connectivity.
The study traces how these players are responding to compounding industry catalysts. Autonomous vehicle integration has transitioned from pilot experimentation to commercial deployment, with driverless ride-hailing services launching in key metropolitan corridors and freight-mobility partnerships accelerating the testing of autonomous integration into existing platform architectures. Simultaneously, public-sector engagement is deepening, as government agencies formalize rideshare procurement pathways, extend membership benefits to workforce populations, and integrate mobility solutions into broader transportation procurement portfolios.
Forces Reshaping the Boardroom: Regulation, Electrification, and Labor Frameworks
No strategic assessment of the ride sharing market would be complete without addressing the regulatory and structural transformations currently recalibrating operational economics. Across major jurisdictions, compliance requirements are evolving from peripheral considerations into core architectural constraints. In North America, environmental mandates are accelerating fleet electrification timelines, with regulatory bodies establishing aggressive zero-emission targets for mobility platforms and tying compliance to measurable greenhouse gas reductions. These requirements are not merely sustainability initiatives; they fundamentally alter capital expenditure planning, vehicle procurement cycles, and total cost of ownership calculations.
Europe’s regulatory trajectory introduces parallel complexity. The impending platform worker directive, scheduled for full implementation in late 2026, will standardize employment benefits and worker protections across digital mobility platforms. This framework is expected to reshape cost structures, influence driver acquisition and retention dynamics, and compel platforms to re-evaluate operational models that rely on highly flexible labor arrangements. For market participants with significant European exposure, compliance readiness and workforce model adaptation will become decisive competitive variables.
At the same time, public-sector mobility procurement is maturing into a structured, long-duration revenue stream rather than a sporadic opportunity. Government-wide purchasing frameworks now encompass multi-year performance periods, integrate civilian and defense mobility needs, and extend ancillary benefits that deepen platform loyalty among institutional user bases. These developments signal a broader paradigm shift: ride sharing is increasingly treated as essential infrastructure, subject to procurement standardization, performance accountability, and integration with public transportation planning.
Why 2026 Demands Precision Intelligence
The 2026 decision environment is defined by simultaneity. Companies must concurrently manage autonomous fleet transition timelines, comply with divergent regional labor and emissions mandates, optimize tiered pricing architectures, and respond to demand patterns that vary sharply across urban, airport, and rural mobility contexts. Aggregate market forecasts alone cannot inform the nuanced trade-offs required at the portfolio, operational, or investment level. Decision-makers need segmentation-level clarity, competitive scenario modeling, and regulatory impact mapping that connect high-level growth trajectories to executable strategic choices.
PW Consulting’s ride sharing market research is constructed to meet that requirement. The study provides a structured reference architecture for evaluating expansion timing, service-tier prioritization, geographic weighting, and partnership strategy. It enables boards and executive teams to assess where concentration dynamics create scale advantages, where regulatory inflection points will alter margin profiles, and where emerging platform models may disrupt incumbent positioning. By synthesizing historical performance, forward-looking growth modeling, and real-time industry catalysts, the report equips stakeholders with the analytical rigor necessary to move from reactive adaptation to proactive strategic design.
Accessing the Full Intelligence Architecture
This introduction offers a strategic preview of the analytical frameworks and industry dynamics underpinning our latest ride sharing market research. The complete study expands far beyond this overview, delivering detailed segmentation analysis, competitive maneuver mapping, regulatory scenario evaluation, and structured insights designed for immediate integration into corporate planning processes. For executives, investors, and strategy leaders seeking to align 2026 initiatives with validated market trajectories, the full report provides the granular intelligence required to convert macro growth signals into disciplined, high-conviction action. We invite decision-makers to access the complete research architecture, where comprehensive data models, detailed corporate profiles, and forward-looking scenario analyses are synthesized into a single, actionable reference for navigating the next phase of mobility market evolution.
For detailed analysis of this topic, please visit the official page: Ride Sharing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lignin Products Market Hits $729.42M in 2025, Projected 4.28% CAGR to $978.1M by 2032
By PW Consulting, 2026-09-16
Unlocking the Potential of Lignin: Strategic Insights for the 2026 Market Landscape
The global transition toward a bio-based economy is no longer a theoretical concept; it is a market reality reshaping supply chains, product formulations, and competitive dynamics across multiple industries. At the forefront of this shift is the lignin value chain. Often dismissed as a byproduct of the pulp and paper industry, lignin has emerged as a versatile, renewable alternative to petrochemical-derived materials. However, realizing its full commercial potential requires more than just technological innovation; it demands precise market intelligence to navigate a complex landscape of regulatory hurdles, fragmented supply sources, and evolving application requirements.
Lignin Products Market
PW Consulting is pleased to introduce our comprehensive market research report on the Lignin Products Market. This study is designed specifically for strategic decision-makers who need to allocate capital, identify partnership opportunities, and mitigate risk in the 2026-2032 forecast period. By combining rigorous quantitative analysis with qualitative competitive profiling, this report serves as an essential compass for navigating the next wave of industrial bioproducts.
Market Trajectory and Growth Catalysts
The lignin market has demonstrated steady resilience and growth over the past half-decade, driven by increasing demand for sustainable industrial inputs. Our analysis tracks the market value from 2020 through the base year of 2025, projecting a continued upward trend into the next decade. In 2020, the global market was valued at approximately 591 million USD. By 2025, this figure has risen to an estimated 729 million USD, reflecting a consistent trajectory of adoption across key end-user sectors.
Looking ahead, the strategic opportunity lies in the forecasted growth window. The market is expected to expand from its 2026 starting point of roughly 767 million USD to nearly 978 million USD by 2032. This projection implies a Compound Annual Growth Rate (CAGR) of 4.28 percent over the forecast period. While this growth rate may appear moderate at first glance, it is essential to contextualize it within the broader chemical industry, where volume growth for traditional bulk chemicals often lags behind specialty bioproducts. The steady CAGR indicates a maturing market that is transitioning from niche experimentation to mainstream commercial viability.
Several underlying drivers are fueling this expansion. First, the regulatory push toward carbon reduction and the circular economy is compelling industries to seek renewable feedstocks. Lignin, as the second most abundant biopolymer on Earth, offers a scalable solution for replacing fossil-based phenols, polyols, and dispersants. Second, technological advancements in separation and purification processes are lowering the cost barrier, making lignin-derived products more competitive against incumbent synthetic alternatives. Third, specific application sectors, such as agriculture and construction, are increasingly recognizing the functional benefits of lignin-based additives, ranging from improved feed efficiency to enhanced concrete setting properties.
Competitive Landscape and Strategic Positioning
Understanding the competitive dynamics is critical for any firm looking to enter or expand within this market. The lignin value chain is characterized by a mix of established pulp and paper giants leveraging their existing biomass access and specialized players focusing on high-value application development. Our report provides a detailed profiling of key market participants who are defining the standard for quality and innovation.
In Northern Europe, companies like Borregaard LignoTech and Domsjö Fabriker represent the legacy strength of the sulfite pulping industry. These organizations have long mastered the extraction and refinement of lignosulfonates. Borregaard, headquartered in Sarpsborg, Norway, continues to lead in specialized biopolymers and lignosulfonates, particularly within agriculture for animal feed binders and organic amendments. Their recent regulatory re-authorization for use in animal feed within the EU in February 2024 underscores the importance of compliance in maintaining market access. Similarly, Domsjö Fabriker in Sweden focuses on sulfite lignin products for agricultural and construction uses, leveraging local infrastructure to secure feedstock continuity.
Finnish competitors are also aggressively positioning themselves through differentiation. UPM Biochemicals has carved a niche in lignin-derived renewable functional fillers. Their collaboration with Nokian Tyres to introduce a concept tire using UPM BioMotion Renewable Functional Fillers highlights the potential for lignin to penetrate high-performance rubber applications. Meanwhile, Stora Enso produces kraft lignin products aimed at wood panel resins and feed binders, utilizing their extensive forestry resources to secure a loyal downstream customer base.
In the Netherlands, LignoStar International B.V. operates as a specialized marketer and seller, focusing on calcium lignosulfonates for animal feed pellet binders and organic amendments. This business model emphasizes distribution agility and technical service support rather than heavy vertical integration. Conversely, the Asian market is seeing the rise of integrated agro-chemical players. Green Agrochem, based in Beijing, operates divisions focused on lignin and lignosulfonates for fertilizer binders, pesticide dispersants, and animal feed applications. Their recent release of technical data sheets for magnesium lignosulfonate in June 2025 demonstrates a focus on product specification and market promotion to capture industrial and agricultural demand.
A critical element of our competitive analysis involves assessing market concentration. The report details the market share distribution among the top players, revealing the level of consolidation and the bargaining power held by key suppliers. This data is vital for understanding pricing dynamics and supply security risks.
Segmentation Analysis: Sources, Products, and Applications
To truly grasp where value is created, one must dissect the market along multiple dimensions. Our report segments the market by source, product type, application, and region, providing a granular view of revenue contributions without relying on broad generalizations.
By Source: The supply of lignin is intrinsically linked to pulping processes. The report quantifies the revenue contribution from Sulfite Pulping, Kraft Pulping, Cellulosic Ethanol, and Soda Pulping. Each source yields lignin with distinct chemical properties and impurity profiles, which in turn dictates suitability for specific downstream applications. For instance, sulfite-derived lignosulfonates are historically dominant in dispersant and binder applications, while kraft lignin is gaining traction in resin formulations and carbon fiber precursors. The analysis highlights which source types are driving revenue growth and where future capacity investments are likely to concentrate.
By Product: The product landscape is primarily divided into Lignosulfonate, Kraft Lignin, and Other Product Types. Lignosulfonates continue to command a significant share of market revenue, driven by their established use across multiple industries. However, the report also tracks the growing revenue potential of specialized kraft lignin derivatives as purification costs decline. The differentiation between commodity-grade and specialty-grade lignin is a key theme, as margins vary significantly between bulk dispersants and high-performance functional fillers.
Lignin and Lignin-Based Products Market
By Application: Demand is driven by diverse end-use sectors including Dispersant, Concrete Additive, and Other Applications. The construction industry utilizes lignin-based additives to improve workability and reduce water content in concrete mixes. In the agricultural sector, lignin serves as a binder in animal feed pellets, which reduces pelleting energy use and improves feed conversion efficiency through better pellet durability. Additionally, lignin acts as a dispersant in fertilizer formulations to ensure uniform nutrient distribution. Our analysis breaks down the relative importance of these applications based on their contribution to total market revenue, helping clients identify the most profitable entry points.
By Region: Geographic revenue distribution is another critical component. The report evaluates performance across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Regional analysis accounts for differences in pulp industry maturity, regulatory environments, and local demand for bio-based materials. For example, European markets often prioritize regulatory compliance and sustainability certifications, while Asian markets may focus on cost-effective industrial scale-up. Understanding these regional nuances allows for tailored market entry strategies.
Industry Dynamics: Regulations, Standards, and Innovation
The lignin market does not operate in a vacuum. A significant portion of our report is dedicated to the external dynamics that shape market behavior, including regulatory frameworks and technological breakthroughs.
Regulatory Environment: Compliance is a gatekeeper in key application segments. In the United States, lignin sulfonate is included on the National List as a synthetic substance allowed for use in organic production under the USDA AMS National Organic Program Document. This designation allows its use as a plant or soil amendment for dust suppression and as a chelating agent in crop production, opening access to the premium organic agriculture sector. In Europe, regulatory approvals have been a focal point. The re-authorization of lignin for use in animal feed within the EU, highlighted by developments involving Borregaard, removes a potential barrier to entry. Furthermore, Sappi Europe gained feed safety certification for lignin-based animal feed applications in October 2024, setting a benchmark for quality and safety that competitors must meet to compete in this high-value segment.
Technological Innovation: The pipeline for new lignin applications is expanding. A notable development is the operation of the LigniOx oxidation process demo plant, which started in January 2026 at the Metsä Fibre Äänekoski pulp mill. Capable of producing up to 2 tons of oxidized lignin per day, this pilot plant represents a step toward commercializing tailored lignin chemistry. Such innovations could unlock new performance characteristics, such as improved solubility or reactivity, which are essential for penetrating more demanding industrial applications like advanced materials or biofuels.
These dynamics create a shifting landscape where regulatory milestones and process innovations can accelerate adoption timelines or alter competitive positioning overnight. Our report synthesizes these events to provide a forward-looking view of market readiness and risk factors.
Strategic Value for 2026 Decision-Making
Why is this report essential for your strategic planning in 2026? The lignin market is at an inflection point where the gap between potential and realization is narrowing, but the path is still complex. Decision-makers need more than top-line numbers; they need actionable intelligence that connects market size to competitive reality.
First, the report provides a robust baseline for investment appraisal. By quantifying the revenue contribution of different sources, products, and applications, companies can prioritize projects that align with high-growth segments. Whether you are considering vertical integration into pulping processes or developing downstream formulation technologies, the segmentation data allows for scenario modeling based on realistic demand forecasts.
Second, the competitive profiling offers context for partnership and M&A strategies. Knowing who holds the market share, who is investing in R&D, and who has secured critical regulatory approvals allows you to identify potential allies or threats. For instance, understanding the specific capabilities of players like Green Agrochem in the fertilizer binder space or UPM in functional fillers can inform supply chain diversification or product differentiation strategies.
Third, the analysis of industry dynamics helps in risk management. Regulatory changes can quickly alter the viability of certain applications. By tracking certifications like feed safety standards and organic compliance, you can anticipate shifts in demand and adjust your product portfolio accordingly. Additionally, monitoring pilot plant operations and technological demonstrations provides early signals of future cost structures and performance capabilities that could disrupt current market equilibriums.
Conclusion
The Lignin Products Market offers a compelling value proposition for companies seeking to align with sustainability goals while capturing new revenue streams. However, success requires navigating a landscape defined by diverse feedstock sources, varied product specifications, and a competitive mix of integrated giants and specialized innovators. PW Consulting's market research report provides the depth and clarity needed to make informed decisions in this evolving environment.
While this overview highlights the strategic framework and key market drivers, it only scratches the surface of the comprehensive intelligence available. The full report contains detailed segmentation breakdowns, competitor analysis matrices, and granular data on regional revenue distributions that are essential for tactical execution. We invite you to access the complete study to gain the full picture of market opportunities and competitive dynamics. Discover how your organization can leverage the growing demand for lignin products to drive sustainable growth and secure a competitive advantage in the bio-based economy.
For detailed analysis of this topic, please visit the official page: Lignin Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Holographic Anti-Counterfeiting Market to Reach $985M by 2032, Growing at 4.0% CAGR
By PW Consulting, 2026-09-16
Illuminating the Path to Authenticity: Strategic Insights into the Holographic Anti-Counterfeiting Marks Market 2026–2032
In an era where counterfeit goods erode brand equity, compromise consumer safety, and violate global trade compliance, holographic anti-counterfeiting marks have evolved from decorative finishes into mission-critical security infrastructure. As regulatory scrutiny intensifies and supply chain vulnerabilities expose high-value products to sophisticated forgery, the demand for optically secure, tamper-evident, and instantly verifiable markings has never been more indispensable. At PW Consulting, we have authored a comprehensive market study that cuts through surface-level industry narratives to deliver an actionable, forward-looking intelligence framework. This article serves as a strategic preview of our latest research, outlining how the holographic anti-counterfeiting marks sector is positioned for measurable expansion, how structural market forces are reshaping competitive boundaries, and why procurement leaders, brand protection officers, and investors require granular, data-backed intelligence to navigate the 2026–2032 horizon.
Market Trajectory and the Strategic Imperative for 2026 Planning
Over the historical review window of 2020 through 2025, the global market for holographic anti-counterfeiting marks demonstrated consistent upward momentum, reflecting a structural shift from reactive anti-fraud measures to proactive, integrated authentication strategies. From a baseline of USD 620.0 million in 2020, market revenue progressed steadily to USD 754.0 million by 2025, signaling that optical security has transitioned from a niche compliance requirement to a mainstream operational priority across multiple product categories. This growth trajectory was not accidental; it reflects sustained industry investment in higher-fidelity optical features, broader deployment of tamper-evident overlays, and increasing reliance on holographic verification as a first-line defense against product duplication.
Looking ahead through the 2026–2032 forecast horizon, the expansion narrative continues with disciplined, compounding growth. The market is projected to advance from approximately USD 770.5 million in 2026 to USD 985.0 million by 2032, underpinned by a forecast period CAGR of 4.0 percent. This trajectory underscores a critical strategic reality for decision-makers: growth will not be driven by volume saturation alone, but by deepening penetration in regulated categories, rising demand for multi-layered authentication architectures, and geographic expansion in regions where enforcement frameworks are maturing. For enterprises mapping procurement budgets, supply chain security investments, and brand protection roadmaps in 2026, understanding how this growth distributes across technology formats, end-use categories, and regional enforcement climates is essential to avoiding misaligned capital allocation.
Our study is engineered specifically to address that planning gap. Instead of presenting a static snapshot, it contextualizes revenue progression within the operational factors that truly shape procurement and investment decisions: the pace of regulatory adoption, the evolution of optical master origination capabilities, the shift toward integrated security supply chains, and the competitive responses of established manufacturers and emerging innovators. By linking historical performance to forward-looking market engineering, the report provides a reliable compass for stakeholders who must translate market size into sourcing strategy, risk mitigation, and growth positioning.
The 2026 Landscape: Regulation, Standards, and Structural Demand Drivers
The current market environment is being redefined by a convergence of policy mandates, standardization initiatives, and technological maturity. One of the most consequential forces shaping demand is the tightening of regulatory frameworks that require visible, easily verifiable security features on high-risk consumer and industrial products. In regulated sectors, the presence of holographic seals is increasingly less about brand aesthetics and more about compliance feasibility, inspection efficiency, and liability management. As authorities enforce tamper-proof visual indicators and authentication protocols, organizations that delay integration of robust optical security face not only legal exposure but also the operational burden of retroactive packaging redesigns and supply chain disruptions.
Parallel to regulatory pressure, standardization efforts are elevating the technical expectations for optical security solutions. Industry bodies are reinforcing guidelines that help organizations verify authenticity, assess performance, and reduce ambiguity in supplier selection. The growing emphasis on documented verification methodologies and structured authentication standards means that procurement teams can no longer evaluate holographic marks solely on visual appearance or unit cost. They must assess durability, replication resistance, integration compatibility, and conformity with recognized authentication frameworks. This shift favors suppliers that can demonstrate technical rigor, repeatable production quality, and alignment with internationally acknowledged verification principles.
On the production side, the technical foundation of high-security holographic marks remains anchored in master origination. The creation of precise optical masters represents the most crucial step in manufacturing secure anti-counterfeiting features, because the fidelity of the final output is directly tied to the quality of the original recording process. Advanced laser-based photoresist recording and specialized origination systems are now essential for producing marks that withstand scrutiny from both end users and counterfeiters attempting replication. As a result, the market is gradually rewarding manufacturers that control or closely integrate master origination capabilities, rather than relying exclusively on commodity-style reprographic workflows.
These dynamics create a dual strategic implication for 2026. First, demand is becoming more specification-driven, with procurement decisions increasingly anchored in performance criteria, regulatory fit, and verification reliability. Second, competitive advantage is shifting toward firms that can offer end-to-end optical security engineering, from master creation to final label or film deployment, while maintaining traceability and consistency across production runs. Understanding how these forces interact across market segments is central to the analytical framework presented in our full study.
Market Architecture: Formats, Applications, and Regional Dynamics Without the Noise
A central challenge for market participants is navigating structural segmentation without losing sight of total-market opportunities. Holographic anti-counterfeiting marks are delivered through multiple physical formats, each with distinct production considerations, integration requirements, and end-use suitability. Broadly, the market is anchored by holographic film-based solutions and holographic paper-based solutions, with film continuing to command the larger revenue share due to its broader adaptability in high-durability packaging, secure labeling, and multi-layer authentication architectures. Paper-based formats remain strategically relevant in applications where cost efficiency, print compatibility, and rapid deployment are prioritized. However, the operational choice between formats rarely hinges on substrate preference alone; it is increasingly defined by the required level of optical complexity, the environment in which the mark must survive, and the verification methods used by downstream inspectors and consumers.
On the application side, demand is dispersed across diverse end-use sectors, with particularly notable reliance in categories where product authenticity carries direct economic and safety implications. Tobacco products continue to represent a substantial share of deployment, driven by regulatory mandates for authentication marks and prominent health-warning compliance. Food and drink applications follow as another major demand channel, where brand trust, supply chain integrity, and consumer safety converge. The cosmetic sector also contributes meaningful volume, reflecting the premium-brand imperative to prevent counterfeiting and protect consumer confidence in high-margin personal care products. Beyond these core verticals, a broad residual category of applications spans documents, pharmaceuticals-adjacent packaging, luxury goods, and industrial components, reinforcing that holographic anti-counterfeiting marks are not confined to a single industry narrative but are becoming a cross-sector authentication layer.
Holographic Anti-counterfeiting Marks Market
Regionally, market distribution reflects the interplay of manufacturing capacity, enforcement maturity, and end-market density. Asia Pacific stands out as a significant revenue region, consistent with its scale in packaging production, industrial manufacturing, and fast-moving consumer goods ecosystems. North America and Europe remain influential demand centers, shaped by stringent regulatory expectations, strong brand-protection cultures, and well-established authentication practices. Latin America and the Middle East and Africa collectively represent meaningful but comparatively smaller revenue pools, with growth potential tied to improving compliance enforcement, expanding export-oriented production, and increasing adoption of standardized security marking practices.
Rather than fragmenting the analysis into isolated percentage breakdowns, our study interprets these structural patterns as interacting forces. It examines where format preferences align with application requirements, where regional enforcement frameworks accelerate adoption, and where supply-side capabilities are redefining market access. This integrated perspective allows readers to see not just where revenue is generated, but why it is generated there and how that positioning is likely to shift through 2032.
Competitive Dynamics: Consolidation, Capability, and the New Innovation Perimeter
The competitive landscape for holographic anti-counterfeiting marks is characterized by a blend of established multinational suppliers, specialized regional manufacturers, and technology-focused entrants expanding the innovation perimeter. Market concentration data indicates a moderately consolidated structure, with the top three players collectively accounting for approximately 45.0 percent of market revenue and the top five reaching around 55.0 percent. This concentration suggests that while scale and integrated capabilities provide meaningful advantages, there remains sufficient space for differentiated specialists to compete on technical novelty, regional responsiveness, and application-specific engineering.
Leading participants illustrate the breadth of strategic postures now shaping the sector. Suzhou Image Technology Co., Ltd. has built a long-standing presence in optical security production, offering custom holographic security labels, hologram stickers, laminate overlays, and anti-counterfeiting solutions with more than two decades of experience in the field. Its recent 20th anniversary celebration in April 2026 reinforced continuity in its security hologram focus, even as the broader market demands more sophisticated integration and verification support. In India, Holographic Security Marking Systems P. Ltd. has positioned itself as a pioneer in holographic security tapes, tamper-evident labels, hologram stickers, and void security seals, reflecting the rising regional importance of practical, enforcement-friendly authentication tools.
Everest Holovisions Limited contributes to the competitive mix through metalized holographic films and security holographic labels designed for enhanced product security, while AFC Hologram specializes in security holograms, holographic registered packaging, lens films, and 3D micro-nano relief structures that push the boundaries of replication difficulty. Shenzhen Holoart High Technology Company Limited and Light Logics Holography and Optics Pvt Ltd further expand the supply base with advanced holographic security features and optical security labels targeting packaging and consumer product authentication. In the flexible packaging and hybrid security domain, Uflex Limited has developed integrated solutions including holographic seals for brand authentication, demonstrating how packaging manufacturers can embed optical security directly into broader product protection strategies.
In Europe, Kurz has long been recognized for holographic security foils, labels, and anti-counterfeiting packaging solutions developed in collaboration with technology partners, highlighting the importance of cross-industry cooperation in maintaining high optical standards. In the United States, Crane Authentication Solutions provides advanced holographic and optical security markings for currency, documents, and products, while in the United Kingdom, De La Rue has advanced optical security through platforms such as OPTILIGHT™, extending holographic applications into high-security environments. HUECK FOLIEN GmbH adds further depth in Europe as a manufacturer of holographic security foils and labels for brand protection and anti-counterfeiting packaging. Kumbhat Holographics rounds out the competitive field as a specialist in holographic security markings and anti-counterfeiting solutions, reinforcing the continued presence of focused, application-oriented suppliers across multiple markets.
Recent industry developments underscore that competition is increasingly defined by collaboration, standardization, and ecosystem expansion as much as by product specifications. In May 2026, IOTA expanded its global anti-counterfeiting dialogue to include banknotes, brand protection, and secure documents, strengthening collaboration with member companies. Earlier in the year, IOTA launched a new membership category for optical security start-ups to foster innovation in anti-counterfeiting technologies, alongside the introduction of the DocCheck Analysts Insights tool to support document verification and authentication for members. These moves matter because they indicate a market in which technology validation, shared verification practices, and access to emerging innovators are becoming integral to competitive resilience.
For enterprise decision-makers, this dynamic environment carries a clear message: sourcing strategy cannot assume static supplier capabilities. Instead, organizations must assess manufacturers not only on current output but on their ability to evolve with regulatory expectations, integrate master origination and replication expertise, participate in authentication ecosystems, and adapt to new verification tools. The full report provides a structured competitive assessment that connects company profiles, strategic focus areas, and recent developments to the practical questions procurement and brand-protection teams face when selecting long-term security partners.
What the Study Delivers: From Macro Signals to Operational Decisions
PW Consulting’s Holographic Anti-Counterfeiting Marks Market study is built to bridge the gap between high-level market awareness and operational decision-making. The report combines long-term market sizing, segmentation interpretation, competitive profiling, and regulatory analysis into a single intelligence framework designed for action. Rather than presenting numbers in isolation, it situates them within the business context that determines their relevance: procurement planning, compliance readiness, technology selection, supplier evaluation, and long-range investment prioritization.
readers can expect detailed coverage of market evolution across the historical and forecast periods, with analysis of how revenue trends reflect shifting demand drivers, format preferences, and application adoption patterns. The study examines the structural logic behind segmentation, helping users understand where holographic film and holographic paper solutions are gaining traction, how application-specific requirements shape deployment strategies, and where regional enforcement and manufacturing dynamics influence market access. It also contextualizes competitive behavior by linking company capabilities and recent milestones to broader market forces, enabling more informed benchmarking and risk assessment.
Equally important is the report’s emphasis on practical interpretation. It addresses the operational significance of optical master origination, the role of specialized production equipment in maintaining high-security standards, and the implications of regulatory frameworks that mandate tamper-proof visual indicators and authentication features. By integrating these elements, the study helps organizations move beyond generic market descriptions and toward precise procurement and strategy decisions. For executives preparing 2026 budgets and three-to-five-year security roadmaps, that interpretive depth is essential. Core quantitative breakdowns, scenario-based sensitivity insights, and vendor-specific benchmarking detail are reserved for the full report, where they can be examined with the precision required for confident decision-making.
Why This Intelligence Matters for 2026 Strategic Planning
The 2026–2032 period will not simply be defined by continued market growth; it will be defined by how effectively organizations translate that growth into defensive advantage and commercial resilience. Holographic anti-counterfeiting marks are increasingly embedded in regulatory compliance, brand protection, and supply chain integrity strategies, which means the cost of incomplete market intelligence is rising. Companies that rely on fragmented data or surface-level market descriptions risk under-investing in the wrong formats, selecting suppliers misaligned with future authentication expectations, or misreading regional demand shifts that affect sourcing and product rollout timing.
This study is designed to reduce those risks. It helps procurement leaders evaluate format and application fit with greater confidence, enables brand-protection teams to align security investments with enforcement trends and verification standards, and supports executives in understanding where competitive concentration creates stability and where emerging innovators may reshape the value chain. With a forecast CAGR of 4.0 percent and revenue projected to approach USD 985.0 million by 2032, the market is large enough to matter and dynamic enough to reward those who plan with precision. The question is no longer whether optical security will continue to grow, but how organizations will position themselves to capture the right opportunities within that growth.
Access the Full Intelligence Framework
This preview has outlined the strategic logic behind the market’s trajectory, the forces reshaping competition, and the operational considerations that should guide 2026 decision-making. It has intentionally avoided presenting the full set of segmented revenue breakdowns, region-by-region percentage distributions, and application-level market shares that form the analytical backbone of the complete study. Those details are essential for precise planning, and they are available in the full report, where each figure is supported by methodological context, competitive interpretation, and implementation relevance.
Holographic Anti-Counterfeiting Trademark Market
For organizations that need to move from market awareness to actionable strategy, the complete PW Consulting Holographic Anti-Counterfeiting Marks Market study offers the depth, structure, and forward-looking perspective required to make informed choices in a rapidly evolving security landscape. To access the full dataset, segmentation analysis, competitive profiling, and forecast decomposition, please visit the source page for the complete market research.
For detailed analysis of this topic, please visit the official page: Holographic Anti-counterfeiting Marks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com